Gold IRA Fees Benchmark 2026: Named Custodian Fee Schedules Compared
What current published fee schedules actually charge: GoldStar Trust and Equity Trust totals side by side at five account sizes, the flat-versus-tiered structures behind them, the dealer markup, and published provider minimums — with the named schedule behind every figure.
View the Fee Data →Educational only: This benchmark records published custodian fee schedules from named primary sources. It does not provide financial, tax, or legal advice. Fees and minimums change; customers should confirm current written pricing directly. Past performance does not guarantee future results.
Key figure
There is no universal annual Gold IRA fee range. Current named schedules use two different structures: GoldStar Trust’s published commingled option is flat at $215 a year whatever the balance, while Equity Trust’s retail schedule is tiered by account value, running $335 a year at $10,000 to $810 at $250,000 non-segregated. The largest cost is usually the one-time dealer markup, which no dealer publishes as a usable per-product schedule; a broad agreement range cannot price a specific purchase.
Sources: GoldStar Trust Fee Schedule for Self-Directed Traditional, Roth, SEP or SIMPLE IRAs and ESAs (current fee schedule, accessed 31 August 2026) and Equity Trust Equity Retail Fee Schedule, Rev. 081726. Both last checked 31 August 2026.
Key takeaways
- Current published schedules contain two different fee structures, so no single annual range describes this market. GoldStar Trust publishes a flat option; Equity Trust and Entrust tier their charges by account value.
- Under GoldStar’s commingled option the annual total is $215 at every balance, so the percentage burden falls from 2.15% at $10,000 to 0.086% at $250,000. Under Equity Trust’s non-segregated option the annual total itself rises with the balance, from $335 to $810, so the burden falls far more slowly, from 3.35% to 0.324%.
- Which structure governs an account therefore matters as much as the account size, and it cannot be read from any market-wide average. It has to be read from the schedule the custodian will actually apply.
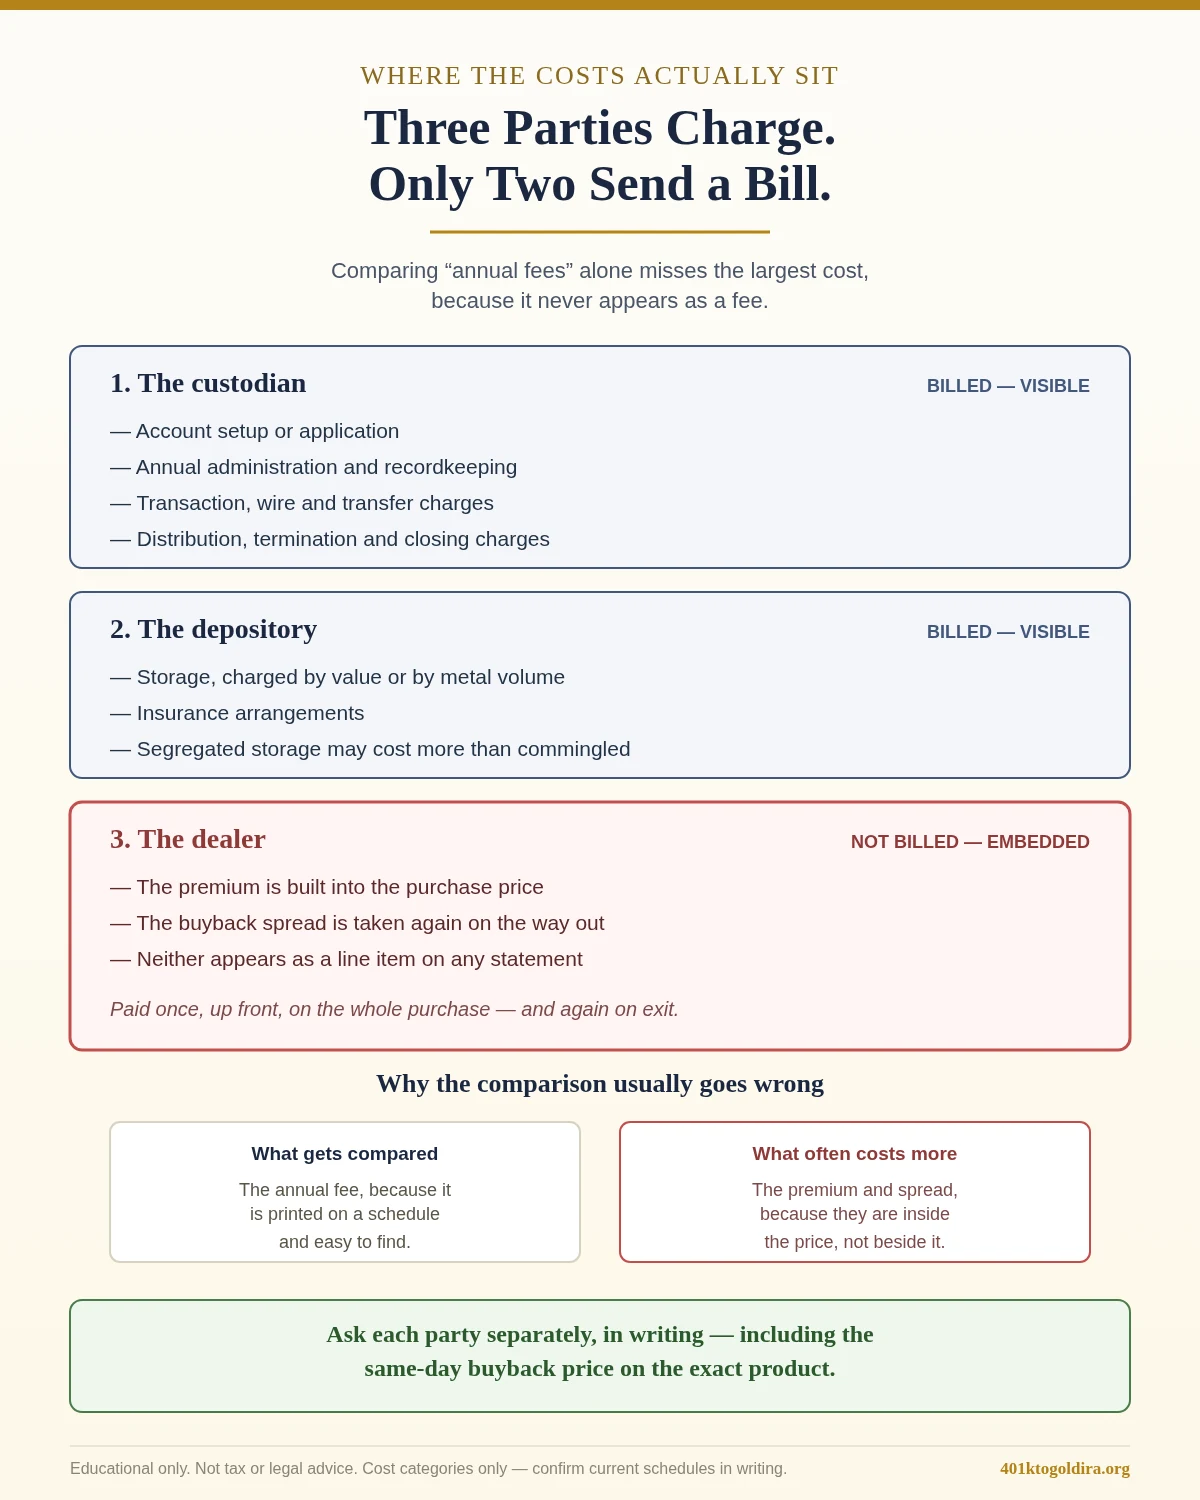
- The largest single cost is normally the one-time dealer markup, which is embedded in the price of the metal rather than billed as a fee. It does not appear on a custodian or depository fee schedule, and it does not appear on an account statement. A CFTC advisory of the CARES Act period placed bullion at spot plus 5%–10%.
- Comparing published fee schedules therefore compares the smaller part of the cost. A schedule can be accurate and still leave the buyer unable to calculate what the transaction costs.
- Provider minimums reported in this market range from approximately $5,000 to $50,000, which determines which providers a given saver can use before any fee comparison becomes relevant.
- Every figure here is read from a named schedule with its revision or observation date recorded. Schedules change — STRATA’s takes effect on 1 September 2026, the day after these were observed — so current terms must be confirmed in writing before funding.
Quick Answer: What a Gold IRA Actually Costs in 2026
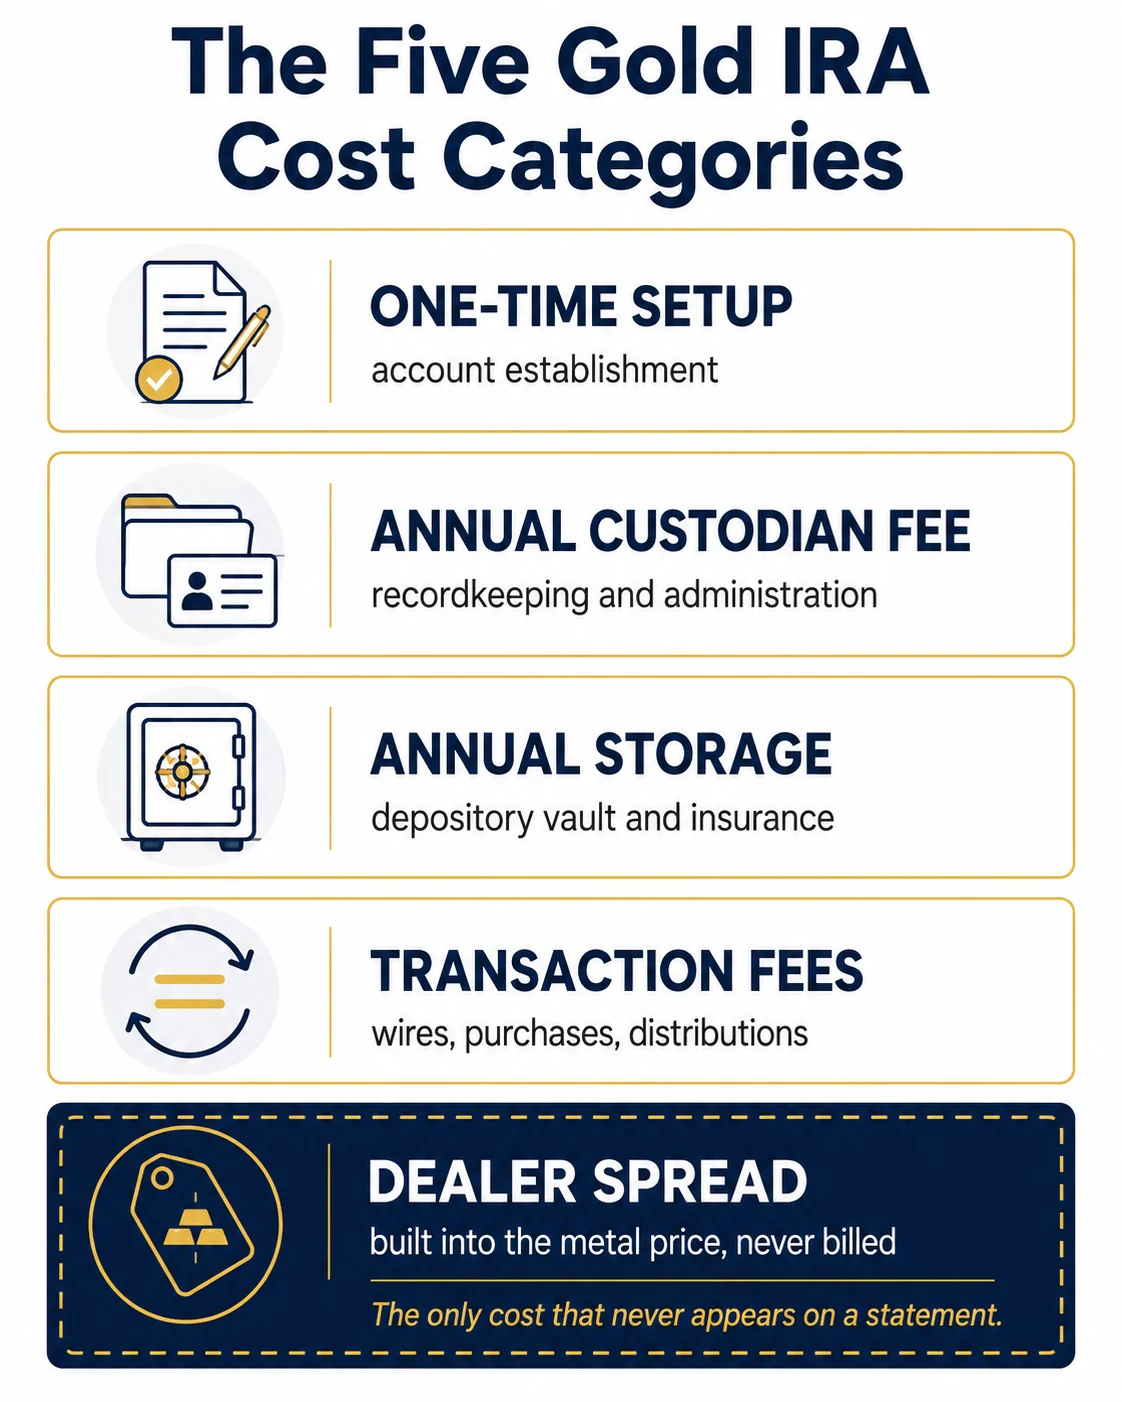
A Gold IRA has five cost buckets: account setup, annual custodian administration, storage and insurance, the dealer markup over spot, and transaction or liquidation fees. There is no universal annual figure for the recurring part, because current published schedules are structured differently. GoldStar Trust’s current schedule produces a flat $215 a year on the commingled option, unchanged from a $10,000 account to a $250,000 one. Equity Trust’s current retail schedule tiers administration by account value, so the same comparison runs from $335 to $810 a year non-segregated. The single largest cost is usually the one-time dealer markup embedded in the metal purchase, which no dealer publishes as a usable per-product schedule; a broad agreement range cannot price a specific purchase. Published provider minimums range from roughly $5,000 to about $50,000.
The Five Gold IRA Cost Buckets and How They Are Structured
Each bucket below is described by its structure, with named examples from current schedules. No market-wide numeric range is published for any of them, and none is asserted here: the figures quoted belong to the specific custodian named beside them, read on 31 August 2026.
| Cost bucket | How it is structured | Named examples from current schedules | Source |
|---|---|---|---|
| Account setup (one-time) | One-off, flat, sometimes waived by channel | Charged once by the custodian to open the self-directed IRA. Published examples across current schedules run from $0 to $100 — STRATA waives it for electronic applications, GoldStar and Equity Trust charge $50 (Equity $75 on paper), Entrust $50 and IRAR $100. These are published examples, not a market average. | Named custodian fee schedules, observed 31 Aug 2026 |
| Annual custodian / admin | Flat in some schedules, value-tiered in others | GoldStar charges a flat $90 precious-metals maintenance fee. Equity Trust tiers administration by account value, from $225 up to $700. Entrust charges $219 for one asset or $329 for two or more, plus 0.17% of value above $50,000, capped at $2,299. NDTCO lists $220 for precious-metals administration and STRATA $150. The structure differs by custodian, so no single figure describes the category. | Named custodian fee schedules, observed 31 Aug 2026 |
| Storage + insurance | Flat, value-based or passed through at cost | GoldStar charges $125 commingled. Its segregated option is quoted as $225 minimum/no maximum, and for values above $125,000 the schedule states a charge of $1.80 per $1,000 of precious-metals value. Equity Trust charges $110 non-segregated or $160 segregated. Entrust and NDTCO pass depository storage through rather than publishing a rate. Segregated storage costs more than commingled in every schedule read. | Named custodian and depository schedules, observed 31 Aug 2026 |
| Dealer markup (over spot) | Embedded in the metal price rather than billed as a fee | The largest and least visible cost. No dealer publishes it as a usable per-product schedule, and a broad range in a customer agreement cannot price a specific purchase. A CFTC customer advisory of the CARES Act period places bullion at spot plus 5%–10% and numismatic coins at 40%–200% above spot. That is a dated regulator statement, not a maintained current average. | CFTC advisory (c. 2020) |
| Transaction / liquidation | Per-event, varies by custodian and depository | Charged per event rather than annually. The schedules read publish these as named per-event line items — typically outgoing wire transfers, distributions, and account termination or closing — each priced individually rather than as a single bundled figure, and some schedules price a precious-metals purchase or sale at $0 while still charging separately for the wire and shipping it requires. The amounts differ by custodian, so no universal range applies and the governing schedule has to be read line by line before funding. | Named custodian fee schedules, observed 31 Aug 2026 |
Custodian and depository schedules are cited by document title and revision or observation date rather than linked, because they are commercial documents rather than regulator publications. Government sources are cited only where they govern the point being made, such as the CFTC advisory on dealer markups.
Why these buckets exist at all
Each bucket above is a consequence of how the law treats metals inside a retirement account, which is why none of them can simply be avoided. Internal Revenue Code section 408 treats the acquisition of a collectible by an IRA as a distribution, and carves out specific bullion and coins from that rule only where they are held by a trustee. That carve-out is the reason a Gold IRA needs a custodian and a depository at all, and therefore the reason setup, administration and storage exist as separate charges rather than being optional services. The depository side states the same arrangement operationally: Delaware Depository’s published FAQ confirms that bullion held in an IRA is controlled by the trustee or custodian and that instructions and reporting pass through that custodian rather than the account holder, which is cited here only for that structural point. The storage-options comparison guide separates those custody rules from insurance, audit-trail and cost questions before a storage quote is compared.
The same framework explains why one of the two structures compared below is value-based. A custodian must report the account’s fair market value annually, so a schedule that tiers administration by account value already has the valuation it needs in order to bill on it. A flat schedule simply declines to use it. The contribution and rollover rules that bring money into the account are in IRS Publication 590-A, and the distribution rules that govern taking metal or cash back out, which is when the transaction and closure charges in the final bucket are incurred, are in IRS Publication 590-B. These are cited for the rules they state, not as sources for any fee figure.
Two Named Schedules Compared by Account Size
This is the question asked most often and answered worst: what does a Gold IRA actually cost at different balances? The honest answer is that it depends on which schedule governs the account, so the table below compares two current named schedules at the same five account sizes rather than publishing one blended average. Every annual total is the schedule’s own arithmetic: GoldStar’s $90 precious-metals maintenance plus $125 commingled storage, and Equity Trust’s value-tiered administration plus its flat $110 non-segregated or $160 segregated storage.
| Account size | GoldStar commingled / yr | Burden | Equity non-segregated / yr | Burden | Equity segregated / yr | Burden |
|---|---|---|---|---|---|---|
| $10,000 | $215 | 2.15% | $335 | 3.35% | $385 | 3.85% |
| $25,000 | $215 | 0.860% | $460 | 1.84% | $510 | 2.04% |
| $50,000 | $215 | 0.430% | $535 | 1.07% | $585 | 1.17% |
| $100,000 | $215 | 0.215% | $610 | 0.610% | $660 | 0.660% |
| $250,000 | $215 | 0.086% | $810 | 0.324% | $860 | 0.344% |
Sources: GoldStar Trust, Fee Schedule for Self-Directed Traditional, Roth, SEP or SIMPLE IRAs and ESAs, current fee schedule accessed 31 August 2026 — $90 annual precious-metals maintenance plus $125 commingled storage. Equity Trust, Equity Retail Fee Schedule, Rev. 081726 — annual administration of $225 ($1–14,999), $320 ($15,000–24,999), $350 ($25,000–49,999), $425 ($50,000–99,999), $500 ($100,000–199,999) and $700 ($200,000–299,999), plus storage of $110 non-segregated or $160 segregated. Both last checked 31 August 2026. Setup fees are one-time and excluded from these annual totals.
The contrast is the point. GoldStar’s commingled total never moves, so its burden falls twenty-five-fold across the range, from 2.15% to 0.086%. Equity Trust’s total more than doubles over the same range, so its burden falls roughly ten-fold, from 3.35% to 0.324%, and stays materially higher at every size shown. Neither is “the market rate”: they are two published schedules, and the structure of whichever one applies is what determines the cost. GoldStar’s segregated option is deliberately excluded from the table because it is value-based: the schedule quotes $225 minimum/no maximum, and for values above $125,000 a charge of $1.80 per $1,000 of precious-metals value. Tabulating it would require assumptions about how those terms combine that the schedule itself does not state. Model a specific scenario on the fee calculator.
The one-time dealer markup, shown separately
The annual totals above are only the billed part of the cost. The dealer markup is charged once, on the metal purchase, and is embedded in the price rather than shown as a fee. At a 5% illustration it would be $500 on a $10,000 purchase, $5,000 on $100,000 and $12,500 on $250,000. That 5% is the conservative end of the CFTC advisory’s dated 5%–10% bullion band from the CARES Act period, used here purely to show the scale of a one-time charge against recurring fees. It is not a current market average, not a quote, and not a rate any dealer in this comparison publishes. On any of the account sizes above, a single markup at that illustrative rate exceeds several years of either schedule’s annual fees.
Structures across the other current schedules
Two schedules cannot describe a market. The table below records what the other current schedules read on 31 August 2026 actually do, which is the evidence for the claim that no single range fits.
| Custodian | Document | Structure | What it charges |
|---|---|---|---|
| GoldStar Trust | Fee Schedule for Self-Directed Traditional, Roth, SEP or SIMPLE IRAs and ESAs (current fee schedule, accessed 31 August 2026) | Flat | $50 establishment; $90 annual precious-metals maintenance; $125 commingled storage. Segregated storage is quoted as $225 minimum/no maximum, and for values above $125,000 the schedule states $1.80 per $1,000 of precious-metals value. |
| Equity Trust | Equity Retail Fee Schedule, Rev. 081726 | Value-tiered | $50 online setup ($75 paper); annual administration tiered from $225 at $1–14,999 to $700 at $200,000–299,999; storage $110 non-segregated or $160 segregated. |
| The Entrust Group | Account Fee Schedule, Revision 01/09/2026 | Value-tiered | $50 setup; $219 a year for one asset or $329 for two or more, plus 0.17% of value above $50,000, capped at $2,299; depository storage passed through. |
| New Direction Trust Company | Current fees page and fee schedule | Flat admin, storage passed through | $220 annual precious-metals administration; depository storage billed as a pass-through rather than a published rate. |
| STRATA Trust | Fee schedule effective 1 September 2026 | Flat (future effective date) | $0 electronic setup or $50 otherwise; $150 precious-metals administration; $115 commingled or $175 segregated storage. This schedule takes effect the day after these figures were observed and did not govern accounts on 31 August 2026. |
Setup charges across these current schedules run from $0 to $100 once electronic-application waivers and IRAR’s $100 are included. That is the spread of published examples, not a market average. Storage is flat in some of these schedules, value-based in others and passed through at depository cost in others again, which is why no single depository range is published on this page.
Seven Custodians, Five Incompatible Fee Structures
Seven named custodian schedules read on 23 September 2026 use five structurally different pricing models: flat; flat plus basis points above a threshold; quarterly and charged per asset; a percentage of account value with a floor and a ceiling; and storage billed externally by a third party. That is the reason no market average exists. It is not that nobody has compiled one. It is that the models are not commensurable, so there is nothing to average.
Madison Trust’s $139 per quarter and GoldStar Trust’s $90 a year are not the same product priced differently. They are different products with different inclusions, billed on different cycles, with storage treated differently in each. An arithmetic mean across the seven rows below would describe nothing that any saver could be charged.
| Custodian | Setup | Annual admin | Storage | Structure type | Source and date |
|---|---|---|---|---|---|
| GoldStar Trust | $50 | $90 a year | $125 commingled, or a $225 minimum segregated, plus $1.80 per $1,000 of value above $125,000 | Flat, plus basis points above a threshold | Fee schedule, Rev. 01/2026 |
| Madison Trust | $50 | $139 per quarter | $100 minimum, then $1 per $1,000 of value above the first $100,000 at Delaware Depository | Quarterly, charged per asset | Fee schedule effective 1 January 2026 |
| The Entrust Group | $50 | $219 a year for a single asset, $329 for two or more | Billed separately by the depository | Percentage above a threshold, capped | Fee page (current schedule accessed 23 September 2026; the page does not state an effective date) |
| STRATA Trust | Not stated on this page | $150 a year | $115 commingled, $175 segregated | Flat | Fee page (current schedule accessed 23 September 2026; the page does not state an effective date) |
| IRA Innovations | $50 | $100 a year | Billed by the storage company; no amount published | Flat, storage external | Precious-metals fee schedule (current schedule accessed 23 September 2026; the page does not state an effective date) |
| Mountain West IRA | $50 | 0.075% of account value per quarter, minimum $32.50 and maximum $75.00 per quarter | Billed separately by the depository | Percentage of value with a floor and a ceiling | Fee page (current schedule accessed 23 September 2026; the page does not state an effective date) |
| Vantage | $50 | $275 a year | 10 basis points of account value, minimum $125 | Flat, plus basis-point storage | Precious Metals IRA fee schedule (current schedule accessed 23 September 2026; the page does not state an effective date) |
Only two of these schedules print an effective or revision date: GoldStar Trust (Rev. 01/2026) and Madison Trust (effective 1 January 2026). The other five were read as the current published schedule on 23 September 2026 and state no effective date, which is recorded above rather than filled in. All seven are commercial documents and are cited in plain text by title and date rather than linked. Advanta IRA was excluded because its schedule could not be retrieved by this site’s fetcher and so could not be verified.
Entrust’s annual charge carries a value component that does not fit the table: the $219 single-asset or $329 multi-asset administration fee is charged plus 0.17% of total asset value above $50,000, with annual recordkeeping capped at $2,299.
Two consequences worth stating plainly
First, two of the seven publish no storage amount at all. Entrust and Mountain West both leave storage to be billed separately by the depository, and IRA Innovations leaves it to the storage company without publishing an amount. For those custodians a quoted “annual custodian fee” is not the recurring cost of the account, because the largest recurring third-party charge is invoiced by someone else and never appears on the custodian’s schedule.
Second, percentage-based schedules mean the same account pays a different fee at different balances. Entrust bills 0.17% of value above $50,000, Mountain West bills 0.075% of account value per quarter between a $32.50 floor and a $75.00 ceiling, and Vantage prices storage at 10 basis points of account value with a $125 minimum. For those three, no single dollar figure can represent the schedule, so any table that assigns them one has already misstated them.
This is the mechanism behind the gap described in what nobody measures, which records that no representative all-in benchmark is published. That section states the absence; this one states why the absence is structural rather than accidental.
Gold IRA Provider Minimums (2026)
Published minimum investments as marketed by each provider. Minimums are a moving target and are sometimes adjusted for promotions or rollover size — always confirm in writing before funding.
| Provider | Published minimum | Positioning |
|---|---|---|
| Preserve Gold | Not published | Obtain the current minimum in writing |
| Birch Gold Group | $5,000 | First-time investors — Birch states the amount can vary with market conditions and product availability |
| American Hartford Gold | $10,000 | Promotions |
| Lear Capital | $10,000 | Diversification focus |
| Noble Gold | $20,000 | Lower-fee positioning |
| Goldco | $25,000 | Service / education |
| Augusta Precious Metals | $50,000 | Education-first, premium tier |
Provider-specific fee detail appears on the American Hartford Gold fees and Augusta fees pages, and a full side-by-side is on the best Gold IRA companies comparison.
Why the Dealer Markup Dominates the All-In Cost
Annual custodian and storage fees are visible and recurring, but they are small relative to the one-time markup on the metal itself. On a $50,000 rollover, a markup difference of even a few percentage points can exceed a decade of annual fees under either schedule compared above. Because the markup is embedded in the purchase price rather than shown as a separate line, it is the cost most likely to be overlooked. The full data on markup ranges is on the dealer markup data page, and an interactive estimate is on the fee calculator.
Regulators describe the same problem in the same terms. The NASAA investor advisory notes that there is no standardized spread, which is the structural reason no dealer publishes a usable per-product schedule, and that buyers are frequently surprised by their first custodian statement because the spread is taken at purchase rather than billed later. The joint CFTC and FINRA investor bulletin of March 2024 makes the same point as a question to ask before buying: the premium over spot has to be requested, because it will not be presented. What those sources do and do not establish is set out by tier in the evidence table below.
What the Evidence Actually Supports, and at What Tier
Published cost figures for this market come from three different kinds of evidence, and commercial articles routinely collapse all three into a single “typical cost” range. They are not the same kind of claim. A regulator advisory stating a range is not a measurement. A figure from an enforcement action is a finding about one named defendant. Averaging them together produces a number that describes nothing.
Read the enforcement rows carefully. The markups established in the Red Rock Secured and Safeguard Metals cases are not market averages and must never be quoted as one. Enforcement populations are selected precisely because the pricing was alleged to be abusive: those buyers were reached by a regulator for that reason. They tell you what has been proven possible in this market, not what an ordinary customer should expect to pay. No source in the table below measures the second thing, which is the subject of the next section.
| Figure | What it measures | Evidence tier | Source and date |
|---|---|---|---|
| 1% to 10% | Dealer spread on ordinary bullion, stated as a typical range rather than measured across a sample. | Regulator-stated No sample size or methodology published. | NASAA, Informed Investor Advisory: Precious Metals and Coin Investments, posted July 2024 |
| Up to about 30% | Dealer markup on numismatic and collectible coins, which the same advisory separates from ordinary bullion. | Regulator-stated No sample size or methodology published. | NASAA, Informed Investor Advisory: Precious Metals and Coin Investments, posted July 2024 |
| 25% to 75% | Drop between what a buyer paid and what their first custodian statement showed, in cases state regulators observed. | Regulator-stated, enforcement-observed Cases observed by state regulators. No denominator: the advisory does not say how many buyers this describes. | NASAA, Informed Investor Advisory: Precious Metals and Coin Investments, posted July 2024 |
| One-third to one-half | Share of a victim's savings consumed by markups, fees and commissions in some gold or silver IRA fraud cases. | Regulator-stated, fraud cases Describes fraud victims specifically, not customers generally. | CFTC and FINRA, 10 Things to Ask Before Buying Physical Gold, Silver, or Other Metals, issued 20 March 2024 |
| 91.89% to 129.97% | Markup over the dealer's own acquisition cost on coins sold to at least 950 customers, who paid over $69 million for coins worth about $30 million. | Court-established case data One named defendant, conduct from about November 2019 to about June 2022. Not a market rate. | CFTC consent order against Red Rock Secured LLC, Release 8898-24, 25 April 2024 |
| About 64% average, range about 30% to over 100% | Markup on silver coin sales to more than 450 mostly elderly investors. The average is in the litigation release; the range is pleaded in the complaint. | SEC and court case data One named defendant. Final judgments entered 2 May 2025. Not a market rate. | SEC v. Safeguard Metals LLC, Litigation Release 26307 (average) and the SEC complaint (range), released 9 May 2025; complaint filed 1 February 2022. See also the SEC complaint. |
| Spot plus 5% to 10% | Premium over spot on bullion, stated generically for precious metals buyers rather than for Gold IRA buyers specifically. | Regulator-stated Generic, not Gold IRA specific, and dated to the CARES Act period. | CFTC customer advisory on precious metals fraud during COVID-19, c. 2020 |
Each figure above was read from the primary document on 23 September 2026. The two NASAA percentages and the CFTC advisory band are statements in investor-education material: no sample, denominator or methodology is published for any of them, so they cannot be treated as measurements. The Red Rock and Safeguard figures are established in a consent order and in SEC filings respectively, for one named defendant over one named period. The broader supervisory context is set out in the joint CFTC, FINRA and NASAA warning of 20 March 2024, the accompanying CFTC flier on Gold IRA sales claims, and FINRA’s investor guidance on buying physical metals.
What Nobody Measures: The Missing Gold IRA Cost Benchmark
No regulator, academic body or industry source publishes a representative all-in Gold IRA cost benchmark by account size. Two independent deep-research passes over the 2024 to 2026 window, prioritising regulator, court, academic and government sources, found none. The figures in the table above are the best evidence that exists, and none of them is that benchmark: the advisory ranges are unmeasured, and the case figures describe defendants rather than a market.
This is worth stating precisely rather than treating as a complaint. The absence is structural. Custodian and depository schedules are published, so the billed part of the cost is knowable. The dealer markup is embedded in the metal price, is not billed as a fee, appears on no statement, and is not reported to anyone who publishes. So the largest component of the cost is the one component nobody collects.
A dataset that actually answered the question would have to report, for a representative sample of real accounts:
- Entry premium over spot on the metal actually purchased, per product
- Account setup charges, including waivers applied in practice
- Annual administration under the schedule that governed the account
- Storage and insurance, segregated and commingled separately
- Transaction costs over the holding period, including wires and shipping
- Dealer buyback discount against spot at the point of sale
- Shipping and closure costs on distribution or account termination
It would have to report these at standardised balances of $25,000, $50,000, $100,000 and $250,000, so that flat and value-tiered structures could be compared at the same sizes. And it would have to state the figure that follows from all of the above and that no published source currently gives: the gold price appreciation required simply to break even, by account size and holding period.
Two kinds of body could publish it. A regulator study from the CFTC, FINRA, NASAA or the GAO, which could compel or request the underlying data, is the most direct route: those bodies already publish the advisory material quoted above, but none has published a representative cost study behind it. Alternatively, academic researchers working with custodian and depository data under confidentiality could construct it, since custodians and depositories jointly hold the billed record and the depositories hold the metal detail needed to reconstruct entry premiums.
Until one of those exists, any single “average Gold IRA cost” figure in circulation is an estimate presented as a measurement. This page states the two things that can be sourced: what named schedules charge, and what regulators and courts have established in the cases they worked.
How to Compare Fees on a Written Quote
To compare providers on a like-for-like basis, request each of the five buckets in writing on the same day: setup fee, annual custodian fee, annual storage and insurance, the exact dealer markup over spot for the specific products quoted, and any transaction or liquidation fees. Then ask for the buyback estimate for those same products. A quote that itemizes all five is far easier to evaluate than one that leads with a promotion. The quote checklist and comparison workbook structure this process.
Reading Published "Best Company" Fee Claims (2026)
As of July 2026, several high-traffic "best gold IRA companies" roundups have begun listing company-level setup, administration, and storage charges directly on the page, making itemized fees a more prominent point of comparison across search results. That shift is useful, but a fee figure quoted in a third-party roundup is a lead, not a confirmed fact. Published lists can lag the provider's current schedule, can blend a dealer charge with a custodian or depository charge, and can omit promotional waivers that expire. Any company-specific number should be treated as "verify in a written company, custodian, or depository disclosure before relying on it."
The reliable step is to separate the three parties a single "company fee" often combines: the dealer (the markup over spot on the metal), the custodian (account setup and annual administration), and the depository (storage and insurance, segregated or commingled). A roundup usually shows one blended figure; a written quote shows all three, dated, for the exact products discussed. Where a provider will not itemize in writing, that itself is a comparison signal. The per-provider verification framework is on the company research guide, and the sourced ranges each figure should be checked against are on the dealer markup data page.
Sources last reviewed: 23 September 2026. The seven custodian schedules and the evidence-tier sources were read on 23 September 2026; the earlier named schedules were read on 31 August 2026, and each table states the date its figures were observed. Published schedules change without notice, so confirm anything material against the custodian’s current document.
Methodology
Every annual figure on this page is read from a named, current fee schedule, identified by document title and revision or observation date, and all were checked on 31 August 2026. The comparison table is not a model: each total is the schedule’s own arithmetic at the stated account size, computed from the published line items and nothing else. Custodian and depository schedules are cited in plain text rather than linked, because they are commercial documents; regulator sources are linked where they govern the point being made.
Three things are deliberately not published here. First, no market-wide annual fee range, because current schedules use both flat and value-tiered structures and any single range or midpoint misrepresents whichever structure it excludes. Second, no multi-year cumulative projection, because that would assume schedules stay unchanged for a decade when one in this set (STRATA) changes the day after these figures were observed. Third, no fee-efficiency threshold, because the balance at which costs become acceptable depends on the structure that applies and is a judgement for the saver rather than a published benchmark.
The one-time dealer markup is shown separately at an illustrative 5%, the conservative end of the CFTC advisory’s dated 5%–10% bullion band, and is never blended into an annual total. Provider minimums are each provider’s own published marketing figure as used across this site. Fees and minimums change frequently and must be confirmed in writing before funding.
External sources are classified by evidence tier rather than cited as equivalent. Regulator advisories, enforcement findings and court-established figures are three different kinds of claim, and the evidence table states which tier each figure belongs to in the same block as the figure itself. No enforcement or court figure is presented anywhere on this page as a market average or a typical cost. Only noncommercial authorities are linked: regulators, courts, the tax code and the IRS. Commercial issuers, meaning dealers, custodians and depositories, are cited in plain text by document title and date, with one exception noted at the point of use, where a depository FAQ is linked solely as evidence of the custodial arrangement rather than for any price. Where a source could not be retrieved by this site’s own fetcher at the time of writing but is a stable government publication cited elsewhere on this site, that is noted rather than concealed.
A correction is worth recording openly. An earlier version of this page published a single universal recurring-fee range, a midpoint derived from it, a claim that such fees are largely flat across the market, percentage burdens calculated from that midpoint, and a ten-year cumulative projection built on all of it. None of those figures was read from a fee schedule, and the flat premise was false as a general claim, because Equity Trust and Entrust both tier their charges by account value. The whole model has been withdrawn and replaced by the named-schedule comparison above, and the withdrawn figures are not repeated here so they cannot be quoted onward.
How to Cite This Page
Source: 401ktogoldira.org — Gold IRA Fees Benchmark 2026: Named Custodian Fee Schedules Compared.
Publisher: 401ktogoldira.org
URL: https://401ktogoldira.org/gold-ira-fees-benchmark-2026/
Sources last reviewed: 23 September 2026 (earlier schedules read 31 August 2026)
Accessed: state the date you retrieved the page, as published fee schedules change without notice.
To cite one schedule or figure rather than the page, append its row anchor to the URL — for example #row-fee-goldstar-trust or #row-size-50-000. Row anchors are derived from each row’s own key and stay stable when rows are added or reordered.
Frequently Asked Questions
What does a Gold IRA cost per year?
It depends on which custodian’s schedule applies, because current published schedules use different structures. Under GoldStar Trust’s current schedule, annual precious-metals maintenance of $90 plus commingled storage of $125 totals $215 a year at every account size. Under Equity Trust’s current retail schedule, administration is tiered by account value and non-segregated storage is $110, so the same account costs $335 a year at $10,000 and $810 a year at $250,000. There is no universal annual range. The larger one-time cost is usually the dealer markup embedded in the metal purchase, which no dealer publishes as a usable per-product schedule; a broad agreement range cannot price a specific purchase.
What is the minimum to open a Gold IRA?
Published provider minimums range from roughly $5,000 at the low end to about $50,000 at the premium end. Common minimums cluster around $10,000 to $25,000. Minimums and fees change and should be confirmed in writing.
What are the five Gold IRA cost buckets?
Account setup, annual custodian administration, storage and insurance, dealer markup over spot, and transaction or liquidation costs. The dealer markup is usually the largest and least visible. Setup and administration are flat in some published schedules and tiered by account value in others, and storage is flat in some and passed through at cost in others, so each bucket has to be read from the specific schedule that will govern the account.
Which Gold IRA fee is easiest to overlook?
The dealer markup, because it is built into the purchase price rather than billed as a separate line item. It can exceed several years of annual fees on a large rollover.
At what account size does a Gold IRA become fee-efficient?
There is no universal threshold, because the answer depends on whether the governing schedule is flat or value-tiered. Under GoldStar Trust’s flat commingled example of $215 a year, the burden falls from 2.15 percent at $10,000 to 0.086 percent at $250,000 because the dollar figure never changes. Under Equity Trust’s value-tiered schedule the annual total itself rises with the balance, from $335 to $810 non-segregated, so the burden falls more slowly, from 3.35 percent to 0.324 percent. The account size at which either becomes acceptable is a judgement for the saver, not a published benchmark.
Update Log
- 24 September 2026: Structural citation pass — stable per-row anchors derived from each row’s own key, row-header scopes, table captions, an expanded citation block with a visible review date, and Dataset metadata describing the variables and method. No figure, schedule, source or observation date was re-verified or changed by this pass; the data still carry their 31 August and 23 September observation dates.
- 23 September 2026: Added a fee-structure section comparing seven named custodian schedules read the same day: GoldStar Trust, Madison Trust, The Entrust Group, STRATA Trust, IRA Innovations, Mountain West IRA and Vantage. The seven use five structurally incompatible pricing models, which is the reason no market average is published here or anywhere else. Two of the seven publish no storage amount because the depository or storage company bills it separately, and three price on a percentage of account value, so no single dollar figure represents them. Only GoldStar (Rev. 01/2026) and Madison Trust (effective 1 January 2026) print a date; the other five are recorded as the current schedule accessed on 23 September 2026 with no stated effective date. Advanta IRA was excluded as unverifiable. No existing figure, table or section was changed.
- 23 September 2026: Added an evidence-tier table separating regulator-stated ranges, enforcement-observed figures and court-established case data, with an explicit warning that enforcement populations are selected for alleged abusive pricing and are not representative of ordinary customers. Added a new section recording that no representative all-in Gold IRA cost benchmark by account size is published by any regulator, academic body or industry source, what such a dataset would have to contain, and who would have to produce it. Expanded the external authority sources from one to more than twelve, each attached to a claim the page already made: IRC section 408 and the IRS publications for why the cost buckets exist, the NASAA advisory and the CFTC and FINRA bulletins for the dealer markup, and the CFTC and SEC enforcement records for the case figures. No fee figure, provider minimum or conversion element was changed.
- 2026 update: Added a "Reading Published Best-Company Fee Claims" section covering the 2026 SERP shift toward itemized company fees and how to separate dealer, custodian, and depository charges before relying on any published figure.
- 31 August 2026: Replaced the modelled universal fee range with a comparison of named current schedules. The previous recurring-fee range, its midpoint, the “largely flat” premise, the percentage burdens derived from them and the ten-year cumulative table have all been removed: none was read from a schedule, and the flat premise is contradicted by the value-tiered schedules now shown. The cost buckets are described by structure with named examples, the dealer markup illustration is separated and labelled as the conservative end of a dated CFTC band, and IRS and FINRA pages were dropped as numeric fee sources.
- 2026: Initial fees benchmark published with the five cost buckets, provider minimum table, methodology, and FAQ schema.
How figures on this site are produced and checked is set out in the research methodology, and errors are handled under the corrections policy. Article reviewed and edited by Daniel — independent precious-metals retirement researcher.